Chocolate Finance Review 2026: Is 3% With No Hoops Too Good to Be True?
Table of Contents
Chocolate Finance pays 3% a year on your first S$20,000 with no salary credit, no card spend and no lock-in. In March 2025, customers pulled out about S$500 million, roughly 40% of its assets, in two weeks.
Both facts are true, and both matter. Fans say it is the simplest way to earn a decent rate on an emergency fund. Sceptics point out that the rate is not a bank rate, is not SDIC-insured, and is backed by a top-up promise with an end date. Which camp you sit in depends on how much you park there and how fast you might need it.
I read Chocolate’s app terms (updated 31 July 2026), its current rate tiers, the card and miles rules, and the reporting on the 2025 withdrawal rush and the funding round that followed. I also set it against Syfe Cash+, T-bills and digital bank accounts. Here is the complete, honest verdict.
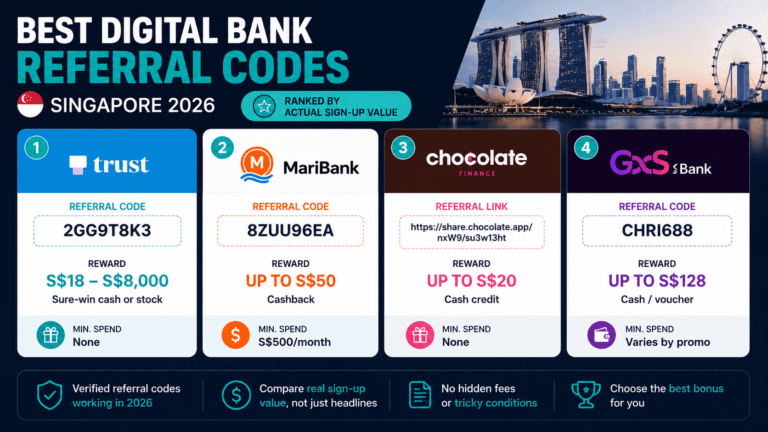
→ Open Chocolate Finance with the DLCuration invite link and get S$15
Chocolate Finance at a Glance
| Factor | Rating |
|---|---|
| Rate on the first S$20,000 | ⭐⭐⭐⭐ 4.4/5 |
| Rate above S$50,000 | ⭐⭐⭐ 3.2/5 |
| Withdrawal speed | ⭐⭐⭐ 3.4/5 |
| Simplicity (no conditions) | ⭐⭐⭐⭐⭐ 4.8/5 |
| Safety and transparency | ⭐⭐⭐ 3.3/5 |
| Visa card and miles | ⭐⭐⭐ 3.6/5 |
| Best for | Savers with S$5,000 to S$50,000 in spare cash who want a fair rate without bank bonus-interest conditions |
| Not ideal for | Emergency money you might need the same day, or anyone who needs SDIC deposit insurance |
| Free plan | Yes — no account fee, no minimum balance, no withdrawal penalty |
| Starting price | S$0 (Chocolate takes its fees from fund returns) |
| Overall rating | ⭐⭐⭐ 3.7 / 5 |
→ Get S$15 when you top up S$1,000 through the invite link
What Is Chocolate Finance?
Chocolate Finance launched in Singapore in 2023. It was founded by Walter de Oude, who earlier founded the insurer Singlife. The idea was a cash account that pays a stated rate with none of the hoops of a bank bonus-interest account.
The company is Chocfin Pte. Ltd. (UEN 202347190R), a fund manager licensed by MAS (CMS101452). Your money goes into a “managed account” of funds that Chocolate selects, aimed at what its terms call “enhanced short duration returns”. In plain terms, that means a mix of money market and short-term bond funds. Custody sits with HSBC, State Street, BNP Paribas and Citibank, and fund dealing runs through Allfunds.
In 2026 Chocolate Singapore offers SGD and USD accounts, a free Visa debit card that earns HeyMax miles, and a “Miles for Returns” option to take your returns as miles. It raised US$15 million in July 2025 from investors including Nikko Asset Management, Peak XV and Prosus, per The Independent SG. Assets had recovered to nearly S$900 million at that point. It launched in Hong Kong in January 2026.
The honest caveat: Chocolate is not a bank. The rate is not guaranteed, your money is not SDIC-insured, and the top-up that keeps the rate steady has an end date.
Chocolate Finance Rates and Fees in 2026: The Full Breakdown
There is no account fee, no minimum balance and no lock-in. Returns are calculated daily and shown in the app from the day after your first top-up. Chocolate says it takes its management and performance fees only after it has delivered the stated rate.
SGD Account — 3.00% on the first S$20,000
- 3.00% a year on the first S$20,000.
- 2.70% a year on the next S$30,000 (S$20,001 to S$50,000).
- Above S$50,000: “up to” 2.70%, with no top-up.
- Rates as of October 2026, from our Chocolate Finance referral page. Chocolate says rates are not guaranteed and can change.
On S$20,000, 3% is S$600 a year. On S$50,000, it is about S$1,410. Best for an emergency fund or a house deposit you will need within a year or two.
USD Account — 4.30% on the first US$20,000
- 4.30% a year on the first US$20,000.
- 4.00% a year on the next US$30,000.
- Above US$50,000: “up to” 4.00%.
- An October 2026 USD Booster adds 1% a year on new USD money above your starting balance, from 1 to 31 October.
Best for people who already hold USD, such as freelancers paid in USD or investors between trades. Converting SGD to USD just for the rate adds currency risk that can wipe out the gap.
The Top-Up Programme — Why the Rate Is Steady
Chocolate’s funds do not always earn the stated rate. When they fall short, Chocolate tops up the difference on the first S$50,000 (or US$50,000) during a “qualifying period”. Its app terms say this period now runs until 31 December 2026, or until assets reach S$2 billion, whichever comes first.
That is the single most important fact in this review. Chocolate has extended the period before — when Financial Horse reviewed it in 2023, it was due to end by 30 June 2024. If it does not extend it again, your return after 2026 becomes whatever the funds earn after fees.
The Chocolate Visa Card — Free, With Miles
- No annual fee and no foreign currency fee on overseas spending.
- 1 HeyMax mile per S$1 on the first S$2,000 of eligible spend each month, then 0.4 miles per S$1.
- The miles rate needs an average daily balance of at least S$5,000.
- Eligible bill payments earn up to 300 miles a month. AXS payments were removed in March 2025.
Hidden Costs to Know About
The rate drops above S$50,000. Every dollar above S$50,000 earns “up to” 2.70% with no top-up. For large balances, a T-bill or fixed deposit can pay more with less risk.
Withdrawals are not instant. Instant withdrawals were suspended in March 2025 and the programme has ended, per the app terms. Withdrawals now take up to three business days. Chocolate says 88% are processed within 24 hours. Keep a few weeks of spending in a bank account.
Fees sit inside the return. You do not see a fee line. Chocolate earns from fund returns above the stated rate. When the top-up ends, those fees will come out of your return instead.
Currency risk on USD. The USD rate is higher, but if the Singapore dollar strengthens, your SGD value falls. A 3% currency move cancels most of a year’s extra interest.
Core Features: What Chocolate Finance Actually Does
A Stated Rate With No Conditions — The Strongest Feature
Bank bonus-interest accounts make you credit your salary, spend on a card, invest or insure to earn their headline rate. Chocolate asks for none of that. You top up by FAST, PayNow or eGIRO and the return appears the next day.
For people who never hit their bank’s spend or salary tiers, this is the whole appeal. A 3% rate with no conditions beats a 7% headline rate you cannot reach.
What Your Money Is Actually In
Your money is invested, not deposited. Chocolate’s terms describe a discretionary managed account of authorised funds — unit trusts, money market funds and ETFs. When Financial Horse tested the account in 2023, its mix was mostly a Dimensional short-term investment-grade bond fund, a UOB Asset Management SGD fund and a Fullerton cash fund. Chocolate can change the mix at its discretion.
Short-term bond funds are low-risk but not risk-free. They can fall when interest rates jump or a bond defaults. While the top-up runs, Chocolate absorbs that shortfall. After it ends, you do.
The March 2025 Withdrawal Rush — What Happened
On 5 March 2025, Chocolate removed AXS bill payments from its miles programme after a surge in use. On 10 March it paused instant withdrawals to manage the volume. Customers read that as a liquidity problem, and about S$500 million left in two weeks.
The company paid out. By 17 March, it said 90% of redemption requests from 10 March had been paid, per Fintech News Singapore. Card spending was capped at S$250, then raised to S$1,000. The requests were met and the funds stayed with the custodians throughout. But the episode showed that a fund-based cash account works differently from a bank when everyone wants out at once.
Miles for Returns and the HeyMax Card
You can convert last month’s returns into HeyMax miles instead of cash. The debit card earns miles on everyday spend if you keep at least S$5,000 in the account. For a frequent traveller, this turns a cash account into a small miles engine. For everyone else, it is a free card with no FX fee — useful on trips. See our best travel credit cards guide if miles are your main goal.
The Honest Assessment: What Holds Up and What Does Not
The custody structure holds up. Client money sits with large custodian banks in segregated accounts, as MAS rules require. If Chocolate itself failed, its creditors could not claim the funds. That is the same structure as Syfe, Endowus and other licensed fund managers.
The rate is real while the top-up runs. Users have been paid the stated rate since 2023, including through the 2025 rush. The question is what happens after 31 December 2026.
Communication has been the weak point. The AXS change in March 2025 was announced with little notice, and the company admitted its communication was inadequate. Rate changes and booster terms still need careful reading in the app.
Not SDIC-insured. Bank deposits are covered up to S$100,000 per bank by SDIC. Chocolate is a fund manager, so that protection does not apply. Your safety rests on custody rules and the quality of the funds, not a government scheme.
Withdrawals are slower than a bank. Up to three business days is fine for most savings. It is not fine for money you might need on a Friday night.
Chocolate Finance vs Syfe Cash+ vs T-bills: Which Should You Choose?
| Factor | Chocolate Finance | Syfe Cash+ Flexi | Singapore T-bills | Digital bank (e.g. GXS) |
|---|---|---|---|---|
| What it is | Managed account of funds | Money market funds | Government debt | Bank deposit |
| SGD rate (Oct 2026) | 3.00% to S$20k, 2.70% to S$50k | Projected, varies with fund yield | Set at each auction | 0.88% Main Account (GXS) |
| Guaranteed? | No (topped up until 31 Dec 2026) | No | Yes, if held to maturity | Yes |
| SDIC-insured | No | No | Not needed (government) | Yes, to S$100,000 |
| Withdrawal | Up to 3 business days | T+1 | At maturity (6 months or 1 year) | Instant |
| Fees | Inside the return | 0.15% a year (Blue tier) | None (cash application) | None |
| Conditions | None | None | Auction timing | None |
GXS rate from our GXS Bank review. Syfe fees from our Syfe review. T-bill mechanics in our T-bills guide.
Choose Chocolate if you have up to S$50,000 of spare cash, want a fair rate with no conditions, and can wait up to three days to withdraw. It is the simplest higher rate on the list while the top-up runs.
Choose Syfe Cash+ if you already invest with Syfe and want cash beside your portfolio, or you prefer a plain money market fund with no top-up promise to expire.
Choose T-bills or a fixed deposit for large sums or money with a known date, such as a renovation next year. Our SSB vs T-bill vs fixed deposit guide explains which fits when. Keep your same-day emergency money in an insured bank account — see our best savings accounts guide.
Who Should Use Chocolate Finance
Chocolate Finance is a strong fit if:
- You have S$5,000 to S$50,000 of spare cash and never hit your bank’s bonus-interest conditions.
- You can wait up to three business days for a withdrawal.
- You hold USD already and want a higher rate on it without buying a fund yourself.
- You travel and want a free card with no FX fee that earns miles.
- You will check the rate and the top-up terms at the end of 2026.
Chocolate Finance is not a strong fit if:
- You need every dollar SDIC-insured.
- This is your only emergency fund and you may need it the same day.
- You have well over S$50,000 to park, where the rate drops and T-bills compete.
- You want a guaranteed rate for a fixed period.
- You do not want to track promotions, boosters and programme end dates.
Is Chocolate Finance Worth It in 2026?
For a mid-sized cash balance, yes, with eyes open. S$20,000 earns about S$600 a year at 3%, against about S$176 at 0.88% in a GXS Main Account. That S$424 gap pays for the three-day withdrawal wait for most people.
The calculation changes at the edges. Above S$50,000 the rate falls with no top-up. And after 31 December 2026, unless Chocolate extends the qualifying period, the rate becomes whatever the funds earn after fees.
The practical test for your first month: top up S$1,000 through the invite link, leave it for 30 days, then withdraw S$100 and time how long it takes. If the return shows daily and the withdrawal lands within three business days, move in the amount you are comfortable with — and set a calendar reminder for December 2026.
Sign-up offer: sign up through the invite link, top up at least S$1,000 and keep it there for 30 days to get S$15. Chocolate uses an invite link, not a code, so downloading the app directly will not track the reward. The Chocolate Finance referral guide walks through each step.
→ Open Chocolate Finance and get S$15
Frequently Asked Questions
Is Chocolate Finance safe?
It is licensed and regulated, but it is not a bank. Chocfin Pte. Ltd. is a MAS-licensed fund manager (CMS101452), and client money sits in segregated custody with HSBC, State Street, BNP Paribas and Citibank. Your money is invested in funds, so it is not SDIC-insured and the return is not guaranteed.
What is the Chocolate Finance rate in 2026?
In October 2026 the SGD account pays 3.00% a year on the first S$20,000 and 2.70% on the next S$30,000. The USD account pays 4.30% on the first US$20,000 and 4.00% on the next US$30,000. Chocolate tops up returns on the first S$50,000 until 31 December 2026 or S$2 billion in assets.
How long does a Chocolate Finance withdrawal take?
Up to three business days. Chocolate says 88% of withdrawals are processed within 24 hours. Instant withdrawals were suspended in March 2025, and the instant withdrawal programme has since ended.
What happened to Chocolate Finance in March 2025?
Chocolate removed AXS bill payments from its miles programme and paused instant withdrawals. Customers withdrew about S$500 million, around 40% of assets, in two weeks. Chocolate paid out the requests within days, capped card spending for a time, and raised US$15 million in new funding in July 2025.
Is Chocolate Finance better than Syfe Cash+?
For a stated rate with no conditions, Chocolate pays more on the first S$20,000 while its top-up runs. Syfe Cash+ Flexi is a plain money market fund with T+1 withdrawals and a visible fee, and its return moves with interest rates. Many savers use one for cash and keep an insured bank account for emergencies.
Who should not use Chocolate Finance?
Anyone who needs deposit insurance, same-day access to every dollar, or a guaranteed rate. It also suits large balances less well, because the rate drops above S$50,000 with no top-up. For those needs, use a bank account, T-bills or a fixed deposit.
Final Verdict
Chocolate Finance earns 3.7 out of 5 stars.
It earns its marks on simplicity. A 3% rate on the first S$20,000 with no salary credit, no card spend and no lock-in is easy to understand and easy to use. Custody with four large banks is sound, and the company paid everyone out during the 2025 rush.
The deductions are about what sits behind the rate. It is not insured, it is not guaranteed, withdrawals take up to three days, and the top-up that holds the rate steady is scheduled to end on 31 December 2026.
Use Chocolate for spare cash up to S$50,000 that you will not need at short notice. Keep your same-day emergency money in an insured bank, and check back when the qualifying period ends.
→ Start with Chocolate Finance through the invite link
Did you stay with Chocolate through the March 2025 rush, or move your money out? Tell me in the comments.
Continue reading: