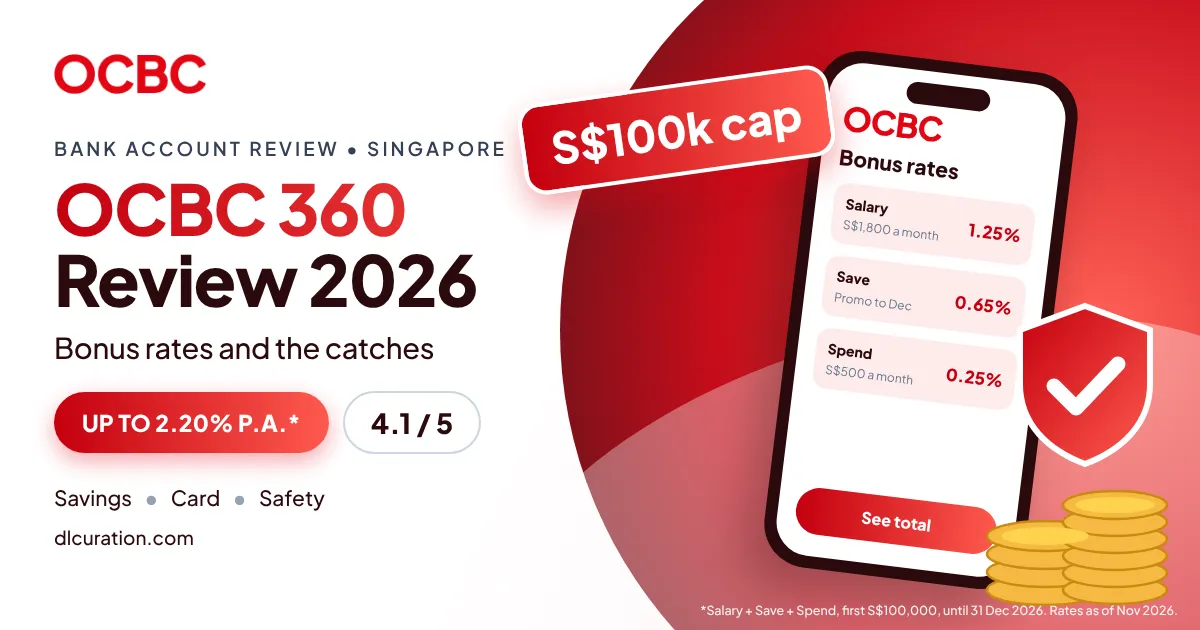
OCBC 360 Account Review 2026: Is It Still Worth Opening?
Table of Contents
The OCBC 360 account has been Singapore’s best-known “bonus interest” savings account for years. You earn a tiny base rate, then stack extra interest by crediting your salary, growing your balance and spending on OCBC cards.
It is still one of the highest realistic rates from a full-service bank. But OCBC cut the bonuses in May 2026, and the best rate now needs more effort than it used to.
I went through the current bonus tiers, the fall-below fee, the new 365 card launching on 1 November, and the referral terms, and set it against Trust, GXS and MariBank. Here is the honest verdict.
→ See the OCBC 360 referral offer and cash rewards
OCBC 360 at a Glance
| Factor | Rating |
|---|---|
| Headline interest rate | ⭐⭐⭐⭐ 4.2/5 |
| Effort to earn the bonuses | ⭐⭐⭐ 3.2/5 |
| Fees and conditions | ⭐⭐⭐⭐ 3.8/5 |
| Safety (full bank, SDIC-insured) | ⭐⭐⭐⭐⭐ 5.0/5 |
| App and branch access | ⭐⭐⭐⭐⭐ 4.6/5 |
| 365 card (new from 1 Nov 2026) | ⭐⭐⭐ 3.3/5 |
| Best for | Salaried workers who can credit S$1,800 a month and keep up to S$100,000 saved |
| Not ideal for | Anyone without a regular salary, or who wants a high rate with no conditions |
| Minimum to open | S$1,000 initial deposit |
| Fees | S$2 a month if your average daily balance is under S$3,000 (waived in year one) |
| Overall rating | ⭐⭐⭐⭐ 4.1 / 5 |
→ Open an OCBC 360 account through the referral link
What Is the OCBC 360 Account?
The OCBC 360 Account is a savings account from Oversea-Chinese Banking Corporation, one of Singapore’s three local banks. As a full bank, Singapore dollar deposits are covered by SDIC insurance up to S$100,000 per depositor per bank, which is the main safety difference from many fintech apps.
The base rate is 0.05% a year. Everything above that comes from bonus categories you unlock. Bonuses apply only to the first S$100,000 in the account. Balances above that go back to the 0.05% base.
You must be 18 or older. Opening needs S$1,000, and you need to keep an average daily balance of at least S$3,000 or pay a S$2 monthly fee. OCBC waives that fee in the first year.
OCBC 360 Interest Rates in 2026
OCBC pays bonus interest in two bands: the first S$75,000 and the next S$25,000.
| Bonus | What you must do | First S$75k | Next S$25k |
|---|---|---|---|
| Salary | Credit at least S$1,800 a month | 1.0% | 2.0% |
| Save | Raise your average daily balance by at least S$500 a month | 0.5% (promo to 31 Dec 2026), then 0.4% | 1.1% (promo), then 0.4% |
| Spend | Spend at least S$500 a month on eligible OCBC cards | 0.25% | 0.25% |
| Insure or Invest | Hold a qualifying product for 12 months | 1.0% | 2.0% |
| Grow | Average daily balance of at least S$250,000 | 1.2% on the first S$100k |
Rates and thresholds are from the OCBC referral page and Beansprout’s August 2026 guide.
What You Actually Earn
Most people use Salary, Save and Spend. Blended over the first S$100,000, that works out to:
- Until 31 December 2026: about 2.20% a year, including the 0.05% base.
- From 1 January 2027: about 1.95%, when the Save promo ends.
Examples: S$50,000 earns about S$900 a year at 1.80% (Salary, Save and Spend on the first S$75k tier). S$100,000 earns about S$2,200 a year at 2.20%.
The Insure and Invest bonuses can lift the maximum to 4.70%, then 4.45% after the promo. But they need an insurance premium of around S$2,000 a year or S$20,000 invested, so I treat them as a bonus for people who already want those products.
The May 2026 Cut
OCBC lowered the bonuses in May 2026. The maximum realistic rate fell from 2.45% to 1.95% on the standard route, and the headline maximum from 5.45% to 4.45%. That is why older reviews quote higher numbers than you will earn today.
The New OCBC 365 Credit Card (From 1 November 2026)
OCBC relaunched the 365 card on 1 November 2026. It now pays 6% cashback on four everyday categories if you spend S$800 a month.
| Feature | Detail |
|---|---|
| 6% cashback | Dining (including fast food), groceries, land transport and petrol |
| Minimum spend | S$800 a month. Under that, all spend earns 0.25% |
| Monthly cap | S$160 cashback (about S$2,667 of 6% spend) |
| Watsons | 3% until 31 March 2027 |
| Everything else | 0.25%, including telco, utilities, EV charging and streaming |
| Annual fee | S$196.20, waived for 2 years, then waived with S$10,000 annual spend |
| FX fee | 3.25% |
| Income needed | S$30,000 (Singaporeans and PRs aged 21 to 55), S$15,000 above 55, S$45,000 for foreigners |
The 6% rate is strong, and the S$800 trigger is the catch. If you miss it in a month, you lose the 6% on all of it. Bills such as telco and utilities earn almost nothing, so the card suits people whose spend is mostly food, groceries and transport.
The card also counts as an eligible OCBC card for the 360 Spend bonus.
Core Features: What OCBC 360 Actually Does
Bonuses on the First S$100,000
If your savings are around S$50,000 to S$100,000 and your salary is credited each month, this is the sweet spot. Beyond S$100,000, extra cash earns just 0.05%, so larger balances belong elsewhere.
Full-Bank Safety and Access
You get a full bank: branches, ATMs, PayNow, GIRO and OCBC’s app. Deposits are SDIC-insured. For many people, that peace of mind is why they pick OCBC over a higher-rate fintech.
Salary Credit Flexibility
The Salary bonus needs at least S$1,800 credited each month. Check with OCBC that your employer’s payment method counts before you move your salary.
The Honest Assessment: What Holds Up and What Does Not
The rate is still competitive for a full bank. Around 2.20% until the end of 2026 is well above the base rates at most banks, and it is insured.
It takes real effort. You need salary credited, a growing balance each month and card spend. Miss a month and that bonus drops out.
The Save bonus is a treadmill. To keep earning it you need to raise your average balance by S$500 every month. That works for a while, then stops being realistic.
The rate is falling. The May cut and the end of the Save promo mean 1.95% from 2027. Plan around that, not the headline 4.45%.
The balance cap matters. Only S$100,000 earns bonuses, so it is not a home for a large cash pile.
OCBC 360 vs Trust, GXS and MariBank
| Factor | OCBC 360 | Trust Bank | GXS | MariBank |
|---|---|---|---|---|
| Realistic rate | About 2.20% to 31 Dec 2026, then 1.95% | About 0.75% to 0.85% | 0.88% base | Up to 1.48% |
| Conditions | Salary, balance growth, card spend | Spend and plan bonuses | Pockets and promos | Salary and ShopeeVIP |
| SDIC-insured | Yes | Yes | Yes | Yes |
| Branches | Yes | No | No | No |
Rates are as of November 2026 and change. See our Trust Bank review, MariBank vs GXS comparison and best savings accounts in Singapore.
Choose OCBC 360 if you have a salary, a few tens of thousands saved and want the highest realistic rate from a full bank.
Choose a digital bank if you do not have a regular salary or do not want to track monthly conditions.
Who Should Use OCBC 360
OCBC 360 is a strong fit if:
- You earn a salary of at least S$1,800 a month that can be credited to OCBC.
- You keep between S$25,000 and S$100,000 in savings.
- You spend at least S$500 a month on an OCBC card.
- You want SDIC protection and branch access.
- You are happy to keep an eye on monthly conditions.
OCBC 360 is not a strong fit if:
- You are self-employed or paid irregularly.
- You hold much more than S$100,000 in cash.
- You do not want to move your salary.
- You want a simple account with no conditions.
- You rarely spend on OCBC cards.
Is OCBC 360 Worth It in 2026?
For salaried savers, yes. Salary, Save and Spend together pay about 2.20% until 31 December 2026 on the first S$100,000, and 1.95% after. That is a few times the rate on a typical digital bank main balance, with the safety of a full bank.
For everyone else, it is a middling account. Without the salary bonus, the rate is poor, and the effort of the Save bonus fades.
The sign-up offer is the tie-breaker for new customers. Cash rewards of up to S$210 on the account plus up to S$365 on the card are available during the campaign.
Sign-up offer: through the referral link, from 1 November to 31 December 2026, you keep S$1,000 in the new 360 account for 30 days or more. You can earn a S$60 Salary reward (S$1,800 a month for 3 consecutive months) and a Top Up reward of S$50 (S$10,000 average daily balance) or S$150 (S$25,000), which also needs salary crediting. That adds up to S$110 or S$210. A S$20 GIRO reward is limited to November accounts and the first 1,000 customers. For the 365 card, spend S$800 within 60 days of approval for S$365 cashback. You must keep the card for 12 months and have had no OCBC credit card in the past 12 months. Rewards are paid by the 15th working day of March 2027 for November accounts, or April 2027 for December accounts. Check the referral page for the full terms.
→ Get the OCBC 360 sign-up rewards
Frequently Asked Questions
Is the OCBC 360 account worth it?
Yes, if you earn a salary of at least S$1,800 a month and keep up to S$100,000 in the account. The Salary, Save and Spend bonuses combined pay about 2.20% until 31 December 2026, then 1.95%.
What is the OCBC 360 interest rate in 2026?
The base rate is 0.05%. With Salary, Save and Spend, about 2.20% on the first S$100,000 until 31 December 2026, then about 1.95%. The maximum rate with Insure and Invest is 4.70%, then 4.45%.
What is the minimum balance for OCBC 360?
You need S$1,000 to open and an average daily balance of at least S$3,000, or you pay a S$2 monthly fee. The fee is waived in your first year.
Is the OCBC 360 account SDIC-insured?
Yes. OCBC is a full bank, so Singapore dollar deposits are covered by SDIC up to S$100,000 per depositor per bank. Credit cards and investments are not.
Why did the OCBC 360 rate drop?
OCBC cut the bonus interest in May 2026, taking the maximum realistic rate from 2.45% to 1.95%. The Save bonus is also on a promo rate until 31 December 2026.
Is the OCBC 365 card good?
It pays 6% on dining, groceries, land transport and petrol, but only if you spend S$800 a month. Under that, all spend earns 0.25%. It suits people whose spending is mostly everyday categories.
Final Verdict
OCBC 360 earns 4.1 out of 5 stars.
It scores well on rate, safety and branch access. For salaried savers with up to S$100,000, it remains one of the best insured accounts in Singapore.
The deductions come from the effort and the cuts. You need salary, balance growth and card spend every month, and the rate is already lower than it was before May and will fall again in January.
Open it if you can meet the Salary bonus. If you cannot, a simpler digital bank may suit you better.
→ Open OCBC 360 through the referral link
Which bank holds your main savings, and does the bonus interest make it worth the effort? Tell me in the comments.
Continue reading: